7 Best Budgeting Methods for Beginners in 2026
Published: 9 Nov 2026
Budgeting sounds boring, and for many people it feels hard too. You track spending for a week, life gets busy, and the plan falls apart. The problem is often not you. The problem is the method. A budgeting method is a set of rules for your money. Some need daily tracking, some need almost none. When the method fits your personality and income pattern, budgeting gets much easier. This guide explains 7 best budgeting methods for beginners in plain words: how each works, who it fits, and what to watch out for. Pick one and try it for two months.
What Is a Budgeting Method?
A budgeting method is a plan for where your money goes before you spend it. It answers three simple questions. How much goes to needs like rent and food? How much goes to wants like eating out and streaming? How much goes to savings and debt? A method gives you those answers in advance. Tracking only shows what you spent; a method tells you what to do next. A budgeting app can track the numbers for you, but the app is only a tool. The method is the plan. If you want help picking a tool, read our guide to the best budgeting apps after you choose a method here.
How to Pick the Right Method
There is no single best method for everyone. The best method is the one you will still use in two months. Ask yourself two questions before you pick. First, what is your personality? If you love details and lists, a strict method will feel good. If you hate tracking, a strict method will feel like a chore and you will quit. Second, how does your income arrive? A steady paycheck every two weeks suits simple percentage rules. Changing income needs a method that works with money in hand, not a guess. A simple method you follow beats a perfect method you drop after one week.
1. The 50/30/20 Rule
The 50/30/20 rule splits your after-tax income into three buckets: 50 percent for needs, 30 percent for wants, and 20 percent for savings and extra debt payments. Needs are rent, utilities, groceries, transport, insurance, and minimum debt payments. Wants are dining out, streaming, hobbies, travel, and new clothes. On a take-home pay of 3,000 dollars a month, that means 1,500 dollars for needs, 900 dollars for wants, and 600 dollars for savings and debt. It is the easiest start because you track only three buckets. The main watch-out is high rent. If rent eats most of your pay, start with 60/20/20 instead.
2. Zero-Based Budgeting
Zero-based budgeting gives every dollar a job before the month starts. You assign your income to bills, groceries, fun, savings, and debt until income minus all plans equals zero. Zero does not mean spent: savings is one of the jobs. For example, with 3,000 dollars of income, you might plan 1,400 dollars for bills, 500 dollars for groceries, 300 dollars for fun, 500 dollars for savings, and 300 dollars for extra debt payments. If your main goal is to pay off debt fast, this method is strong, because every spare dollar gets a clear job instead of drifting away. It suits detail lovers who want full control. The watch-out is time: it works best after one or two months of real spending data.
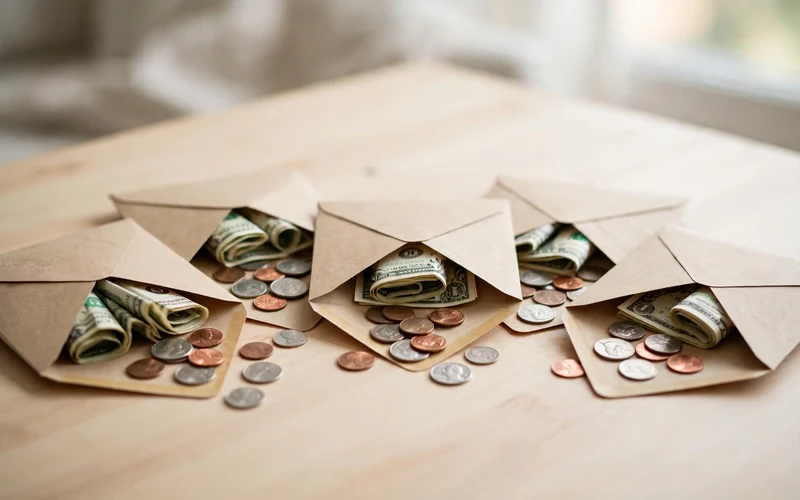
3. The Envelope Method
The envelope method is a cash system with a hard limit you can feel. At the start of the month, you take out cash for each spending category and put it in a labeled envelope. Groceries get one envelope, dining out gets one, fun money gets one. When an envelope is empty, spending in that category stops until next month. That hard limit is the whole point. Digital envelopes in an app work the same way. This method is best for people who overspend on one or two categories, like takeout or clothes. The watch-out is a cashless world. Many places now take cards only, so use cash envelopes for your weak spots and a card for fixed bills.
4. Pay Yourself First
Pay yourself first flips the usual order. Instead of spending first and saving what is left, you save first and spend what is left. On payday, an automatic transfer moves a set amount to savings before you can spend it. Then pay bills and spend the rest freely. If you save 300 dollars from a 3,000 dollar paycheck, you live on the other 2,700 dollars however you like. It removes willpower from saving: people who wait until month-end usually find nothing left. Once the transfer is automatic, put the saved money toward passive income ideas that build over time. The watch-out is that it does not control spending, so keep a rough eye on total spending.
5. The 80/20 Rule
The 80/20 rule is the simplest method on this list. You save 20 percent of your income and spend the other 80 percent on everything else, needs and wants together. There are no categories and no tracking beyond the savings transfer. On a 3,000 dollar paycheck, you move 600 dollars to savings and live on 2,400 dollars. That is the whole method. It suits busy people, minimalists, and people whose spending is already fairly reasonable. The watch-out is the same as pay yourself first, only stronger. With no categories at all, a spending problem can hide for months. If you carry high-interest debt or often run out of money before payday, a method with more structure will serve you better.
6. Values-Based Budgeting
Values-based budgeting starts with what matters to you, not with a fixed percentage. You list your top three values, such as health, family time, or learning a skill, and you shape your spending around them. Money flows toward those values first. Spending that does not match any value gets cut first. For example, if cooking at home and weekend trips with family are your values, you might cut streaming subscriptions and impulse shopping, then move that money to groceries and a trip fund. It suits people who hate strict rules but still waste money on things they do not value. The watch-out is honesty: it only works if you name your real values. Pair it with an automatic transfer so you still save.
7. Reverse Budgeting
Reverse budgeting starts from a savings goal and works backwards. First you pick a clear target, such as saving 6,000 dollars in one year. That means 500 dollars a month. Then you look at your income, take out the 500 dollars, and build your spending plan around what is left. Unlike pay yourself first, a habit, this is goal-first planning: the target sets the number, and you adjust spending until the math works. It suits savers who need a clear finish line. If the numbers do not fit, raise income, cut spending, or stretch the deadline. A goal that is too big only leads to quitting.
A Worked Example: The Same 3,000 Dollars, 7 Ways
Imagine a take-home pay of 3,000 dollars a month. All figures are illustrative only. The 50/30/20 rule gives 1,500 dollars for needs, 900 for wants, 600 for savings and debt. Zero-based budgeting assigns all 3,000 dollars: 1,400 for bills, 500 for groceries, 300 for fun, 500 for savings, 300 for debt. Envelopes might hold 500 dollars for groceries, 200 for dining, and 150 for fun. Pay yourself first moves 300 dollars to savings on payday. The 80/20 rule saves 600 dollars and spends 2,400 freely. Values-based budgeting might send 400 dollars to a trip fund and cut 200 dollars of low-value shopping. Reverse budgeting leaves 2,500 dollars after a 500 dollar goal. If 3,000 dollars feels far from your real pay, our low income saving tips show how to start small.
Budgeting Methods Compared
| Method | Effort | Best For | Watch Out |
|---|---|---|---|
| 50/30/20 rule | Low | Beginners, steady income | Tight when rent is high |
| Zero-based budgeting | High | Detail lovers, debt payoff | Needs real spending data |
| Envelope method | Medium | Overspenders, visual thinkers | Awkward in cashless world |
| Pay yourself first | Very low | People who never save | No spending control |
| 80/20 rule | Very low | Busy people, simple finances | Hides spending problems |
| Values-based budgeting | Medium | People who hate strict rules | Needs honest values |
| Reverse budgeting | Low | Goal-driven savers | Goal can be too high |
What If Your Income Changes Every Month?
Many beginners earn a different amount each month, from freelance work, part-time jobs, or seasonal hours. Budget with your lowest recent month, not your best month. If you earned 2,200 dollars in a slow month and 3,400 dollars in a good month, build the plan on 2,200 dollars. Treat extra income as a bonus. Zero-based budgeting shines here, because you only assign money that has actually arrived. Pay yourself first also works if you save a percentage of each payment. Students and part-time workers often face this problem, and side hustles for students can add income, but the budget still needs a base month. Keep a small buffer for slow weeks.
Your 30-Minute Setup Plan
You can set up a working budget in 30 minutes. Minutes 0 to 5: write down your take-home pay for this month, using your lowest recent month if income varies. Minutes 5 to 10: list your fixed bills, rent, utilities, transport, insurance, and minimum debt payments. Minutes 10 to 15: pick one method and write its main rule down. Minutes 15 to 25: set up one automatic savings transfer for payday, even 50 dollars. Minutes 25 to 30: set a weekly 10-minute check to review spending. A rough plan you use beats a perfect plan you never finish. After one month, adjust the numbers and keep going.
Can You Combine Methods or Switch?
Yes, and most people end up doing it. A popular mix is the 50/30/20 rule plus pay yourself first: the automatic transfer handles the 20 percent savings part, and the percentages handle the rest. Or use envelopes for your two worst categories, with the 80/20 rule for the rest. Values-based budgeting pairs with any method, since it shows what to cut. Give each method a fair test: try one for 60 days before you judge it. If a method still feels wrong after two honest months, switch without guilt.
Mistakes to Avoid
- Picking the strictest method first when you hate tracking, then quitting in week two.
- Budgeting with your best month instead of your lowest month.
- Forgetting irregular costs like car repairs, gifts, and yearly fees.
- Cutting all fun money to zero, then splurging later.
- Setting a savings goal so high you fail in month one.
- Judging a method after one bad week, not 60 days.
- Tracking every penny but never acting on what the numbers show.
FAQs
What is the easiest budgeting method for beginners?
The 50/30/20 rule is the easiest starting point. It uses three buckets and takes about 15 minutes to set up. If that feels like too much, start with the 80/20 rule.
How much should a beginner save each month?
Aim for 20 percent of take-home pay, but any regular amount is a good start. If 20 percent is too much, start with 5 or 10 percent.
What is zero-based budgeting in simple words?
It means giving every dollar a job before the month starts, so income minus plans equals zero. Savings counts as a job too, so zero does not mean spent.
Is the envelope method still useful today?
Yes, for people who overspend in one or two categories, because cash creates a hard limit. If most spending is by card, use cash envelopes only for your weak spots.
Which budgeting method is best for irregular income?
Zero-based budgeting, because you only assign money that has arrived. Budget with your lowest recent month and review the plan every payday.
Can I use more than one budgeting method at once?
Yes, such as the 50/30/20 rule with pay yourself first. The mix only needs to be simple enough to keep up.
How long does it take for a budget to work?
Give any method at least 60 days. The first month teaches your real numbers. Most budgets feel easier after two to three months.
Do I need a budgeting app to follow these methods?
No. Every method here works with a notebook and a pen. An app can make tracking faster, but the method matters far more than the tool.
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
