When to Start Investing: A Simple Guide for Beginners
Published: 1 Oct 2026
When should you start investing? For most people, the answer is simple: start when your basic finances are stable and you have money that you can leave invested for the long term. You do not need a large amount of money to learn how investing works and begin building the habit.
When Is the Right Time to Start Investing?
There is no single age or perfect income level for investing. The right time depends on your financial situation, goals, debt, savings, and ability to handle market changes. If you can cover your basic needs and keep some money invested for years, you may be ready to start.
- Check your monthly income before investing.
- Know your regular living expenses.
- Keep money aside for emergencies.
- Deal with expensive debt first.
- Decide why you want to invest.
- Invest only money you can leave untouched for your goal.
Start Small Instead of Waiting for a Large Amount
Many beginners wait because they think investing needs thousands of dollars. That idea can delay your progress for years. You can start with a small amount, learn how your chosen investment works, and increase your contribution when your income grows. The habit matters more than a big first deposit.
- Start with an amount that fits your budget.
- Set a small monthly investing goal.
- Increase your amount after a pay raise.
- Automate regular contributions when possible.
- Avoid borrowing money to invest.
- Focus on building a long-term habit.
Get Your Basic Finances Ready First
Investing should support your financial life, not make everyday money problems harder. Before putting money into the market, look at your cash flow and short-term needs. An emergency fund can help you handle unexpected costs without selling investments when prices are low. Investor.gov also separates emergency savings from long-term investing.
- Create a simple monthly budget.
- Build an emergency savings fund.
- Pay attention to high-interest debt.
- Keep short-term money easy to access.
- Separate savings from investment money.
- Review your finances before increasing investments.
Why High-Interest Debt Matters
High-interest debt can grow faster than many people expect. Credit card balances are a common example. If you carry expensive debt, paying it down can be an important financial step before increasing long-term investments. Investor.gov also advises investors to consider paying down high-interest debt as part of building wealth.
- Check the interest rate on your debt.
- List debts from highest to lowest interest.
- Pay more than the minimum when possible.
- Avoid adding new high-interest debt.
- Keep a small cash reserve for emergencies.
- Revisit investing after your debt becomes manageable.
Understand Compound Growth Before You Invest
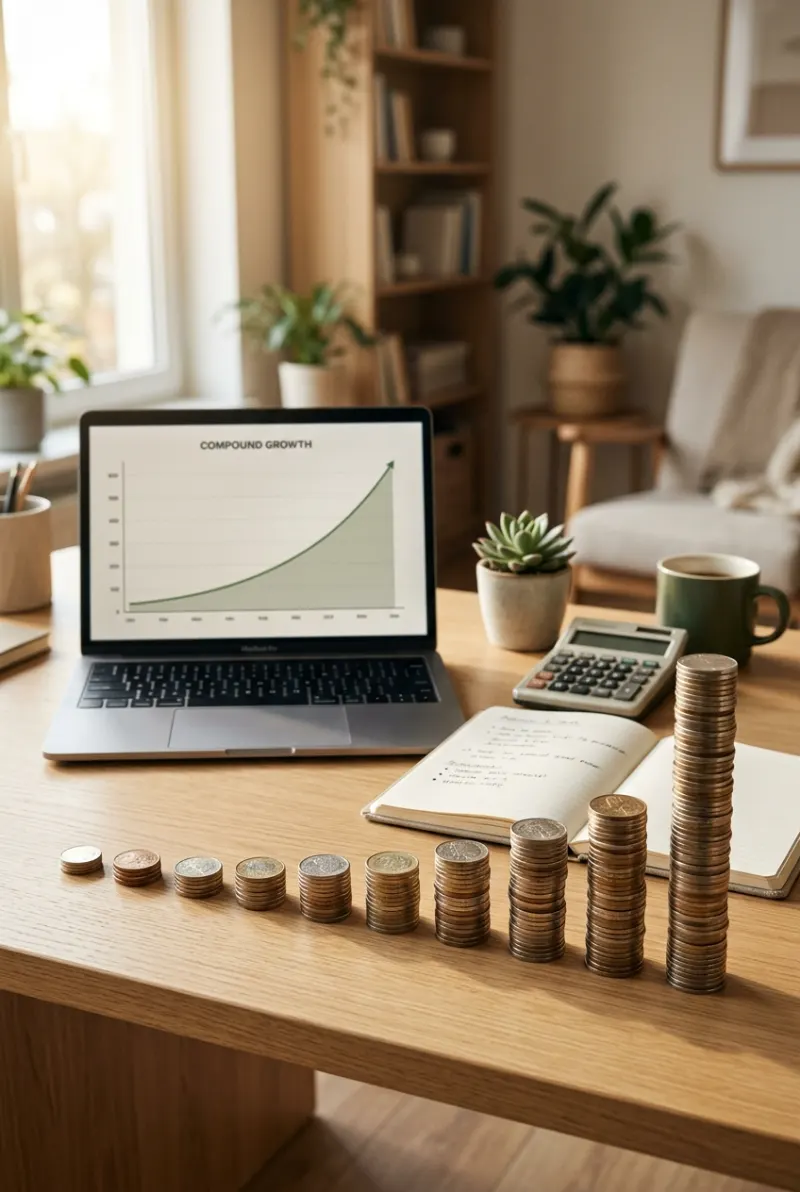
Compound growth means your investment can earn returns, and those returns can remain invested and potentially earn more returns. Time gives this process more room to work. That is why starting earlier can matter, even when your first investment amount is small. However, investment returns are never guaranteed.
- Your original money can grow over time.
- Reinvested returns can add to future growth.
- Regular contributions can increase your invested amount.
- A longer time period gives growth more time.
- Market returns can rise or fall.
- Compound growth does not remove investment risk.
A Simple Example of Starting Early
Imagine two people who invest regularly but start at different ages. The person who starts earlier has more years for contributions and potential growth. Investor.gov uses long-term examples to show how the monthly amount needed for a future goal can increase when someone starts later.
- Start early if your finances allow it.
- Do not wait for a perfect market.
- Give long-term investments enough time.
- Keep contributing through market ups and downs.
- Increase contributions as your income grows.
- Remember that examples are not guaranteed returns.
Personal lesson: One mistake beginners often make is waiting until they feel “rich enough” to invest. A better approach is to learn with an amount that does not hurt your monthly budget. Starting small can teach you more than spending years waiting for the perfect moment.
Choose an Investment That Matches Your Goal
Investments work differently, so your choice should match your goal and time frame. Stocks, bonds, mutual funds, ETFs, and real estate all carry different risks and costs. Investor.gov notes that your investment choices should consider factors such as risk, return, fees, diversification, and liquidity.
- Decide when you will need the money.
- Think about how much loss you can handle.
- Compare investment fees.
- Learn how easily you can access your money.
- Spread money across suitable investments.
- Understand an investment before buying it.
Index Funds and ETFs
Index funds aim to follow a market index instead of trying to pick individual winning stocks. They can give investors exposure to many securities through one fund. Some index funds may also have lower costs because they use a passive strategy, but fees and risks still vary between funds.
- Learn which index the fund follows.
- Check the fund’s fees.
- Look at its major holdings.
- Understand the level of market risk.
- Check whether the fund fits your goal.
- Avoid buying a fund only because it is popular.
Dividend-Paying Stocks
Dividend-paying stocks are shares of companies that distribute part of their earnings to shareholders. Some investors like dividends because they can provide cash income, but a dividend does not make a stock risk-free. Share prices can fall, and companies can reduce or stop dividend payments.
- Research the company before buying.
- Check the company’s financial history.
- Look at dividend sustainability.
- Remember that dividends are not guaranteed.
- Consider the stock’s total return.
- Avoid choosing a stock only for a high dividend yield.
Real Estate and Property Investing
Real estate can be another way to invest, but buying property usually requires more money and comes with costs such as maintenance, taxes, insurance, and financing. Beginners can also learn about real estate investment trusts, or REITs, which can provide real estate exposure without directly buying a property.
- Calculate the full cost of owning property.
- Consider maintenance and repair costs.
- Think about rental income carefully.
- Research the local property market.
- Learn how REITs work before investing.
- Avoid assuming property prices always rise.
Crowdfunded Real Estate
Crowdfunded real estate allows investors to participate in property projects through online platforms. It may offer access to projects that would be difficult to buy alone. However, these investments can have different fees, risks, holding periods, and rules. Always research the platform and investment before committing money.
- Research the platform and its fees.
- Understand how your money will be used.
- Check the expected investment period.
- Learn when you can access your money.
- Review the risks of the specific project.
- Never invest just because a project promises high returns.
Retirement Accounts Can Be a Starting Point
Retirement accounts can help people invest for long-term goals while receiving certain tax benefits, depending on their country and account type. In the United States, examples include 401(k) plans and IRAs. Workplace plans may also include employer matching contributions, which can add value to employee savings.
- Check whether your employer offers a retirement plan.
- Understand any employer contribution or matching program.
- Learn the account’s tax rules.
- Check contribution limits.
- Review the investment choices inside the account.
- Choose investments that match your retirement timeline.
For U.S. readers: The IRS says the 2026 employee contribution limit for most 401(k) plans is $24,500, while the combined annual contribution limit for traditional and Roth IRAs is $7,500, subject to the applicable rules. These limits can change, so check current IRS information before making contribution decisions.
How Old Should You Be When You Start Investing?
There is no universal “perfect age” for investing. A teenager with earned income, a person in their 20s, or someone starting in their 40s or 50s can have different opportunities and needs. Your age matters, but your goal, income, savings, time horizon, and risk tolerance matter too.
- Start when your financial foundation supports it.
- Use your age to think about your time horizon.
- Consider how soon you need the money.
- Match investment risk with your goal.
- Keep learning as your situation changes.
- Do not assume you are too old to begin.
Starting in Your 20s
Your 20s can give you a long investment time horizon. You may have decades before retirement or another major goal. This extra time can give compound growth more opportunity to work, although market prices can still move up and down. Building a regular investing habit can be useful during these years.
- Learn basic investing terms.
- Start with a manageable contribution.
- Use employer retirement benefits when available.
- Build an emergency fund.
- Avoid taking unnecessary investment risks.
- Increase contributions as your income improves.
Starting in Your 30s
Starting in your 30s does not mean you have missed your chance. You may have a stronger income and clearer financial goals than you had earlier. Your focus can shift toward balancing retirement investing with other goals, such as buying a home, starting a business, or supporting a family.
- Set clear financial goals.
- Review your retirement savings.
- Increase contributions when possible.
- Keep short-term goals separate.
- Diversify your investments.
- Review your plan at least once a year.
Starting in Your 40s or Later
Starting later can still help you build wealth, but you may have less time before you need the money. That can affect how much you need to save and how you manage risk. Investor.gov notes that starting later may require larger regular contributions to reach the same long-term target.
- Calculate your remaining investment time.
- Set a realistic retirement target.
- Review your current savings.
- Consider increasing regular contributions.
- Avoid taking extreme risks to catch up quickly.
- Get professional advice when your situation requires it.
Do Not Try to Predict the Perfect Market
Many beginners ask whether they should invest today or wait for prices to fall. Nobody can reliably know exactly when the market will reach its lowest point. A long-term plan can help you avoid making every investment decision based on daily market movements or short-term news.
- Focus on your investment time horizon.
- Invest according to your financial plan.
- Avoid emotional buying and selling.
- Do not chase sudden market trends.
- Review your portfolio instead of checking it constantly.
- Remember that all investments carry risk.
Diversification Can Help Manage Investment Risk
Diversification means spreading your money across different investments instead of depending on one company or asset. It cannot guarantee that you will avoid losses, but it can reduce the effect of one investment performing badly. Funds can make diversification easier, although a narrow fund may still lack broad diversification.
- Avoid putting all your money into one stock.
- Consider different companies and sectors.
- Learn about stocks, bonds, and funds.
- Check what an ETF or mutual fund actually owns.
- Review whether your investments overlap.
- Match diversification with your personal goals.
Make Investing a Monthly Habit
Regular investing can be easier when you treat it like a normal monthly expense. You do not need to check the market every day. A simple schedule can help you keep adding money while focusing on your long-term goals. Automation can also reduce the number of decisions you need to make.
- Choose a monthly investment amount.
- Set an automatic contribution if available.
- Increase the amount after income growth.
- Keep investing within your budget.
- Review your plan at set times.
- Avoid changing your plan because of every market move.
Personal lesson: I find that simple money systems are easier to follow than complicated plans. If you have to make a new investing decision every week, you may eventually stop. A small automatic contribution can turn investing into a normal financial habit instead of another task on your list.
Common Investing Mistakes Beginners Should Avoid
New investors often focus on how much money they can make. A better starting point is understanding what can go wrong. Investment scams, high fees, poor diversification, emotional decisions, and unrealistic return promises can hurt your results. Investor.gov also warns investors about scams that promise easy or guaranteed high returns.
- Do not invest because someone promises guaranteed profits.
- Do not invest money you need for bills.
- Do not ignore investment fees.
- Do not copy random social media trades.
- Do not put everything into one investment.
- Do not buy something you do not understand.
A Simple Investing Checklist for Beginners
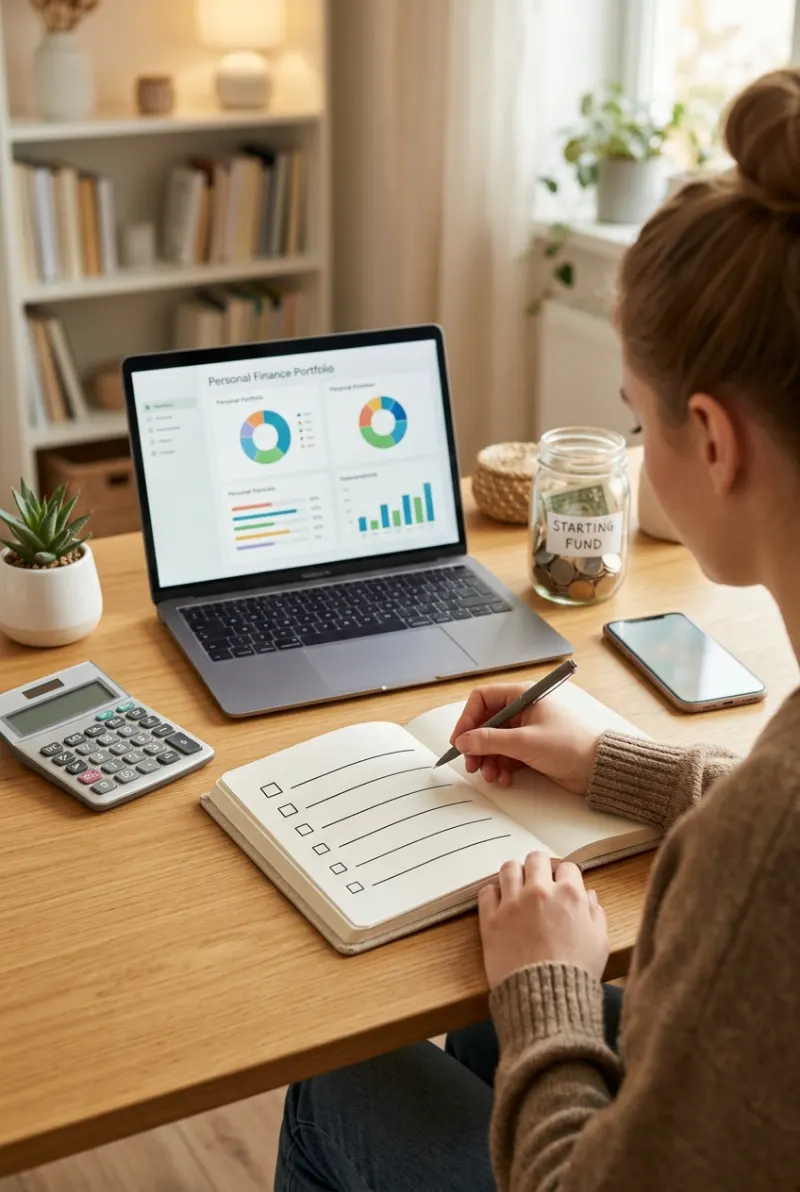
You do not need a complicated strategy to take your first step. Start by checking your financial foundation, setting a goal, learning the basics, and choosing an investment that matches your time horizon and risk level. This process can help you make calmer decisions and avoid common beginner mistakes.
- Step 1: Check your income and monthly expenses.
- Step 2: Build an emergency fund.
- Step 3: Deal with high-interest debt.
- Step 4: Choose a clear investment goal.
- Step 5: Learn about suitable investment options.
- Step 6: Start with an amount your budget can handle.
So, When Should You Start Investing?
The right time to start investing is usually not about finding a perfect age or predicting the perfect market day. It is about reaching a point where you can invest for the long term without risking money needed for basic expenses. Starting small, learning the basics, and staying consistent can build a strong foundation.
- Start when your basic finances are stable.
- Keep emergency money separate from investments.
- Pay attention to expensive debt.
- Choose investments that match your goals.
- Think about risk before chasing returns.
- Give long-term investments enough time.
- Increase contributions as your finances improve.
- Keep learning before trying complex investments.
Remember: Investing can help you build wealth over time, but it always involves risk. The value of investments can fall, and you can lose money. Your goal should be to understand what you are buying and why it fits your financial plan.
Final Thought
If you have been asking yourself, “Am I too young to invest?” or “Did I start too late?”, focus on what you can control today. Learn one concept, check your finances, choose a realistic goal, and take one sensible step. You do not need to know everything before you begin.
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
